Where the VCs Think All This Is Headed
VC memos are useful not because they perfectly predict the future, but because they force a public bet on where the next winners might get built.
Mar 31, 2026
I find VC memos useful for a very specific reason: they are forced to do the hard part in public. It is easy to tell a story about who AI might disrupt. It is much harder to say where the next winners get built. Right or wrong, memos like Logan Bartlett's Redpoint market update and Sequoia's Services: The New Software are attempts to place that bet.
That is what makes them worth reading.
Below are a few notes after going through both.
Why These Two Stood Out
- Redpoint is trying to explain why public software is getting repriced without collapsing into a lazy "SaaS is dead" narrative.
- Sequoia is trying to name a new winner shape: software companies that quietly sell the work instead of the tool.
- The useful part is not whether every category call is right. It is that both are trying to say where value accrues next.
As a founder, that matters to me.
My time is effectively my portfolio. I do not get to spray small checks into twenty bets. I get to concentrate my time into one thing at a time. So I care a lot about any framing that helps me think more clearly about where the next real companies get built.
Software Got There First Because It Is Mostly Intelligence Work
Sequoia starts with a point that feels directionally correct: software engineering moved first because so much of it is intelligence work.
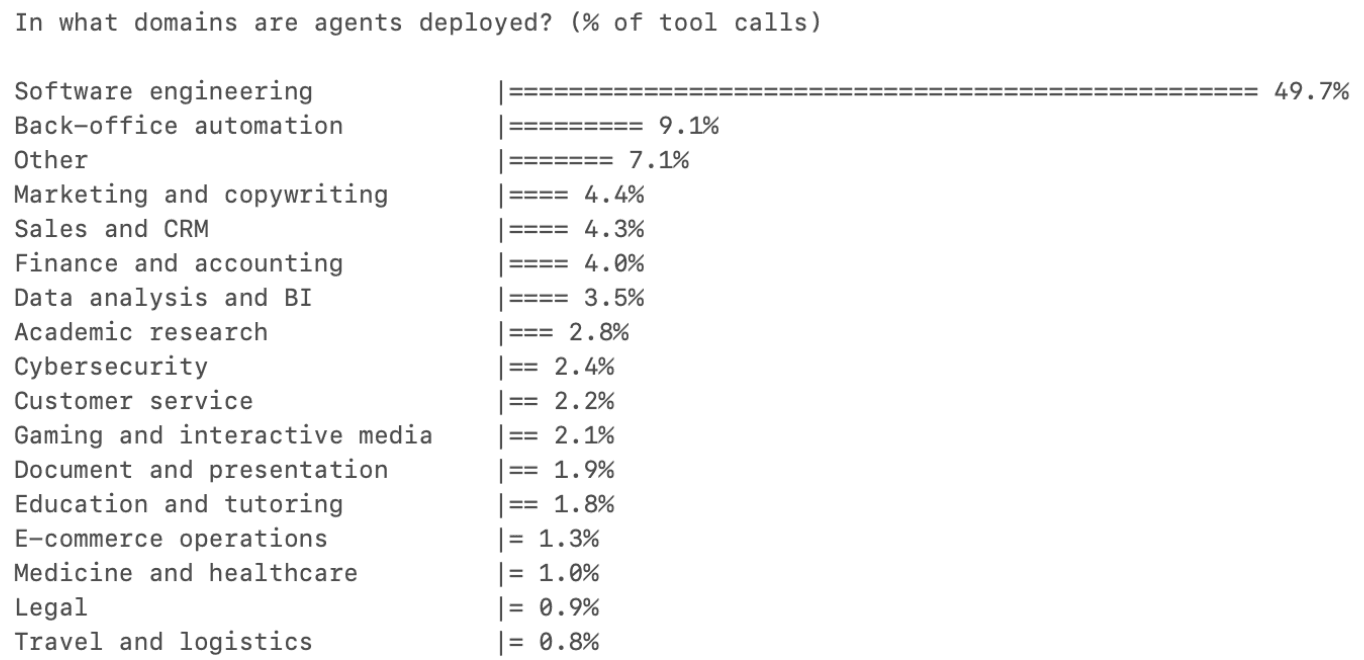
- Translating a spec into code, debugging, testing, and wiring systems together are hard, but they are still mostly rule-bound.
- That does not mean software requires no judgement. It obviously does.
- But it does mean AI can already absorb a huge amount of the work while humans still hold onto the judgement layer.
This matches my own experience pretty closely. The broad market is still mostly living in the copilot or task-agent phase. Meanwhile, if you live inside coding agents long enough, you can already get into workflow-agent territory. My own coding agents have been running for an hour or more at a time for a while now.
So I like Sequoia's framing here, even if I think the transition is happening faster than many people realize.
Judgement vs Intelligence Is a Useful Split
The most useful image in the Sequoia piece is not the category list itself. It is the map.
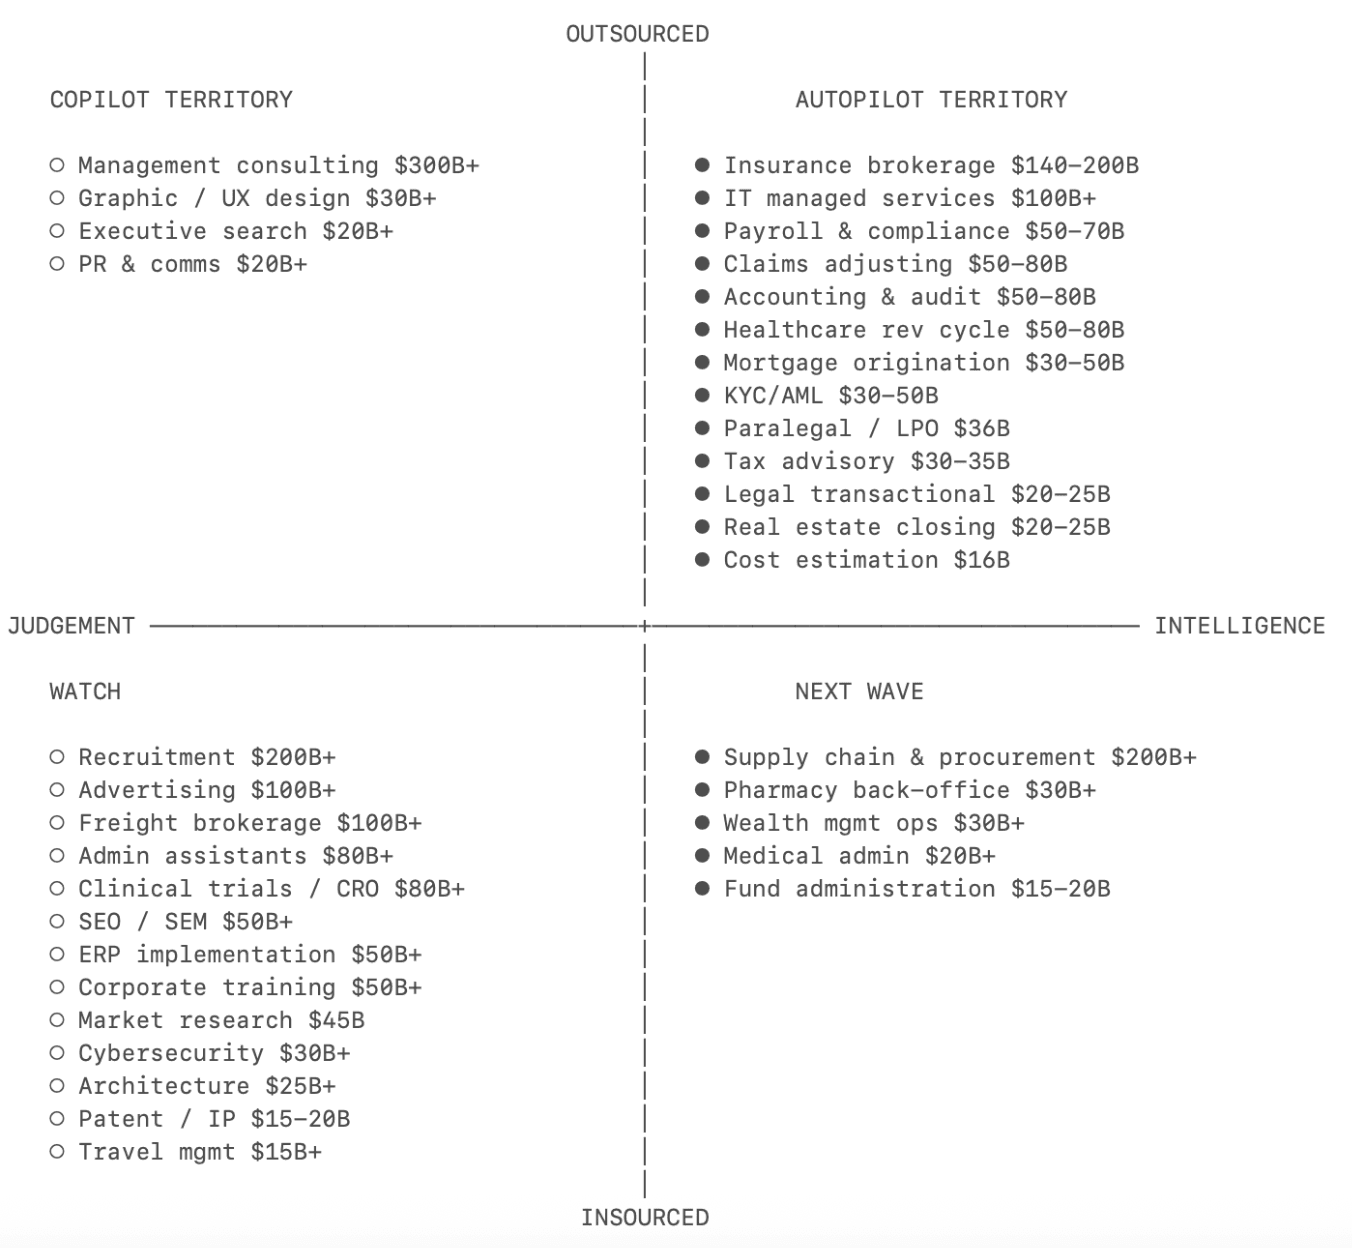
- I really like the judgement versus intelligence split.
- Intelligence feels like math, physics, coding, research synthesis, or finding the correct answer across a huge body of information.
- Judgement feels closer to taste: what ad is better, what joke is funnier, what color is better, what culture is right, what feature should ship next.
That is useful because it maps pretty cleanly to something I have been thinking about a lot already: taste.
I have written before that taste is becoming more valuable, but I think what I actually mean here is judgement. Taste is just one expression of that. The software part can increasingly do the intelligence work. The thing that stays scarce longer is the judgement about what matters, what is good, and what should happen next.
I also like the insourced versus outsourced split because it is really a proxy for cultural friction.
- If work is already outsourced, switching vendors is a relatively clean substitution.
- If work is insourced, replacing it means touching org charts, staffing, identity, politics, and internal resistance.
- It is easy to switch an insurance broker. It is much harder to tell a whole internal team that the software now does their job.
That makes outsourced intelligence work feel like the most obvious beachhead for disruption.
Decay Is Usually Slower Than The Panic Narrative
One of the most useful Redpoint slides is the newspaper analogy.
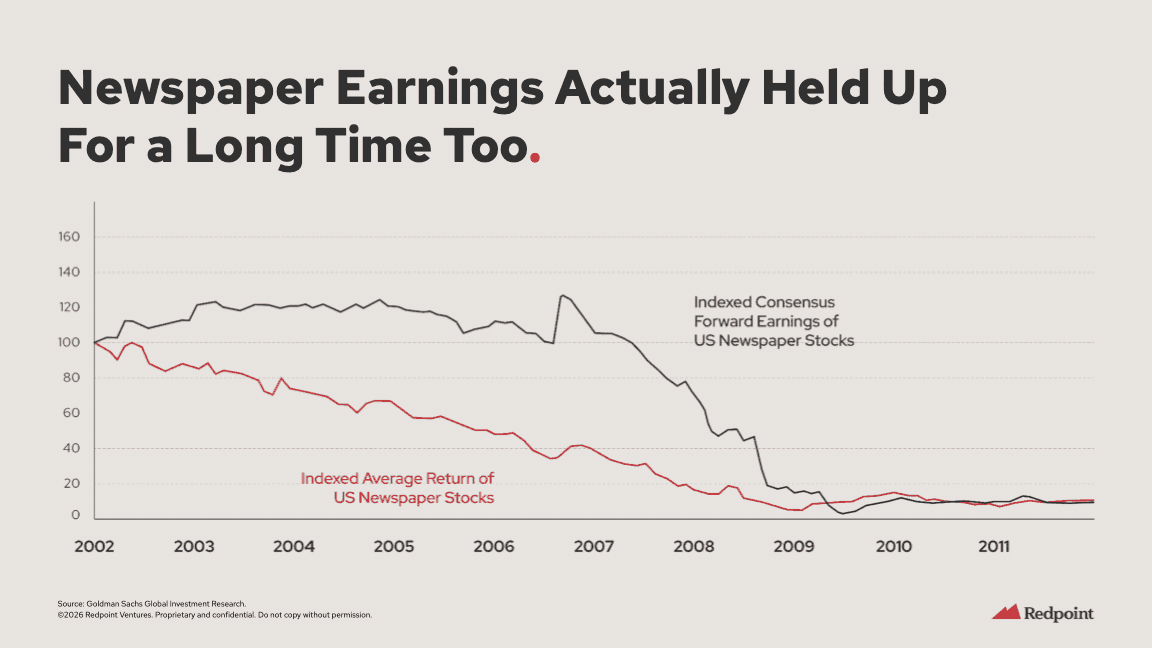
- I often come back to examples like newspapers, bank tellers, or elevator operators.
- The direction of the change can be obvious long before the reported numbers fully crack.
- That does not mean the disruption is fake. It means transitions take time to work through the system.
This is why I find the current "SaaS apocalypse" framing too shallow.
Some companies will absolutely get repriced correctly. Some will probably get repriced unfairly. Some will look fine for longer than people expect before the real damage shows up. That is normal. The panic narrative usually moves faster than the business reality.
Public Markets Are Arguing About Terminal Value
This might be the most useful chart in the Redpoint deck.
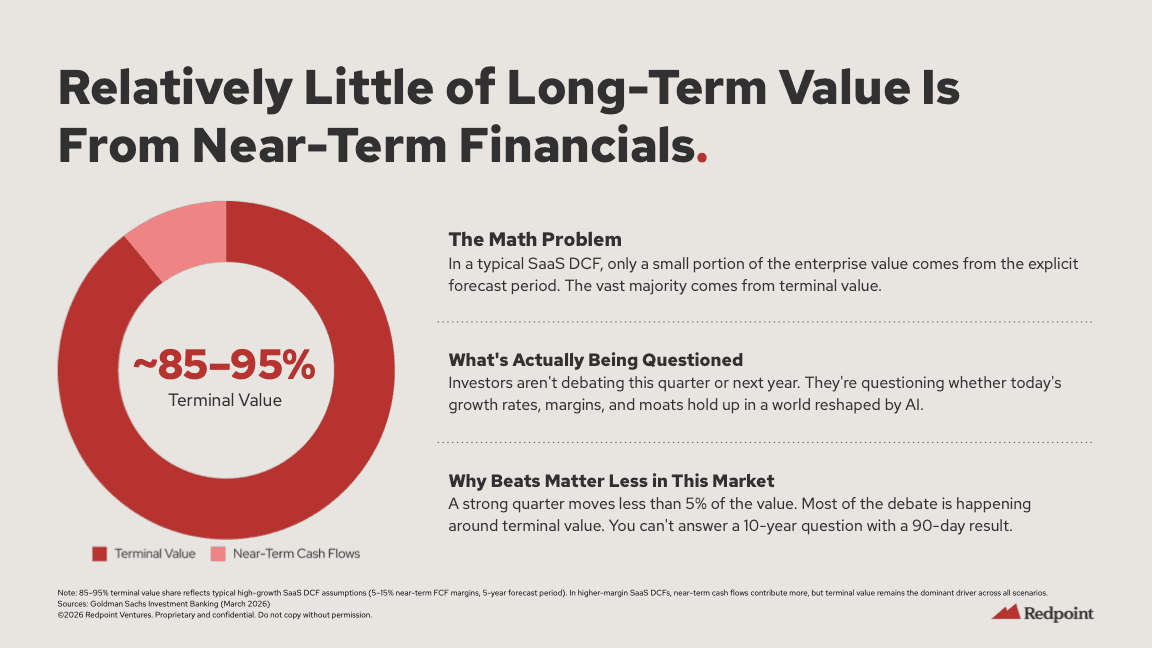
- If 85-95% of the value is in terminal value, then a strong quarter does not really settle the core debate.
- The market is not arguing about this quarter. It is arguing about the next decade.
- That makes a lot of the AI repricing story easier to understand.
You cannot answer a ten-year question with a ninety-day result.
That is also why the newspaper comparison is useful. The underlying concern is not "are these companies still making money right now?" The concern is "what does this business look like once the software layer gets abstracted away by agents, autopilots, or outcome-driven competitors?"
The Hard Part For Incumbents Is Not Trust. It Is Re-Founding
I found the usual "incumbents get preferential treatment" argument a little bland. Of course they do. Trusted vendors, existing relationships, and known brands have always mattered.
The harder question is whether incumbents can actually re-found themselves around the new product shape.
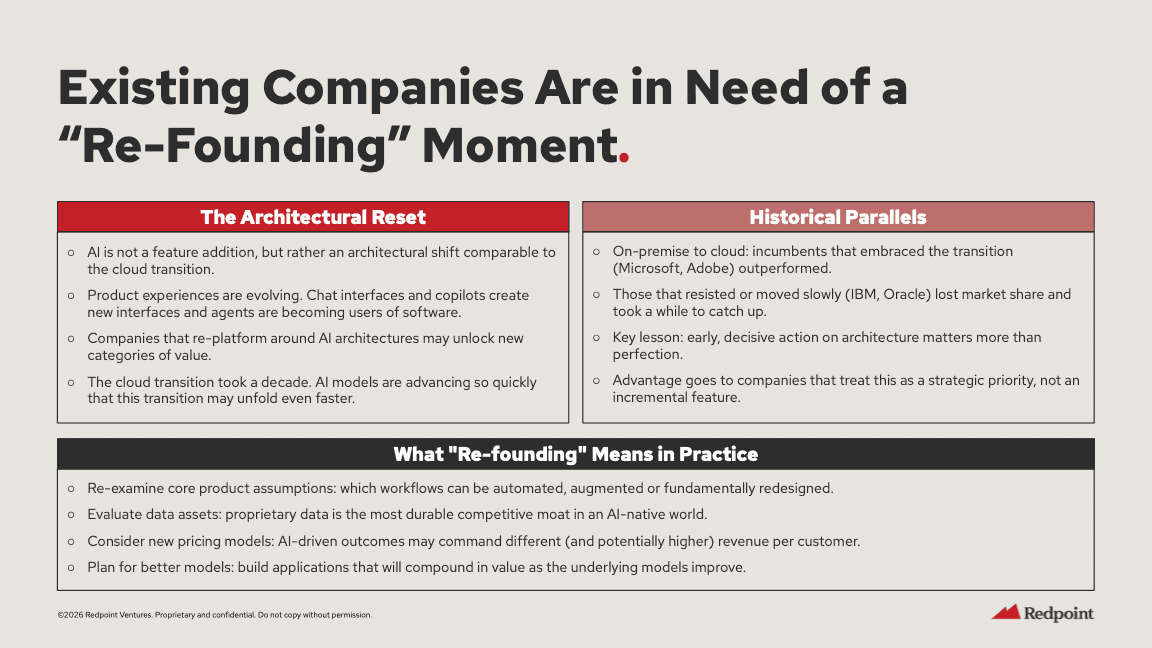
- Startups do not have to drag legacy customers through the transition.
- They get to chase early adopters and product-market fit with people who want the new thing.
- Incumbents have distribution, but they also have installed-base gravity.
That tension feels real.
If I were running a public software company, I would not only bolt AI features onto the existing product. I would ask what the agent-native version of this business looks like if the software fades into the background and the customer just buys the outcome.
That is a much scarier question.
Because once an agent-native layer abstracts your product away, the old switching costs can start to look less durable.
What I Think Is Interesting Here
- I do not read these memos because I think VCs have the answers.
- I read them because they are some of the few people forced to publicly say where the winners might be.
- That is much harder than telling a disruption story.
A few things feel directionally right to me after reading both:
- Some of the best AI businesses may hide the software entirely and sell outcomes, rituals, and value instead.
- Outsourced work gets disrupted first because the barrier is cultural, not just technical.
- Absorbing frontier model progress is table stakes, not a moat.
- Old moats like distribution, brand, and operational excellence still matter a lot.
- New moats may come from proprietary judgement data, especially where raw model intelligence becomes easier to access than hard-won domain judgement.
I do not think that means "software becomes services" in one clean sweep.
I think it means we are going to get a lot of AI-native software, a lot of agent-native software, and a lot of human service businesses that quietly get turned into software because software can finally do the work.
That feels like the more interesting transition.
Parting Thoughts
The biggest value of these memos is not that they predict the future perfectly.
It is that they force a better question:
Not just who loses, but where the next winners get built.
As someone trying to form my own founder thesis for the next decade, I find that useful. My time is my capital. I want to spend it where value is actually going to accrue.
Right or wrong, these memos are attempts to point at that future in public.
That alone makes them worth reading.